
LEVERAGE™ CASE STUDY
Portland Total Loss Appaisal - State Farm Total Loss Claim: Appraisal Clause Dispute Over a 1991 Volvo 240 in Portland, Oregon
Portland, Oregon
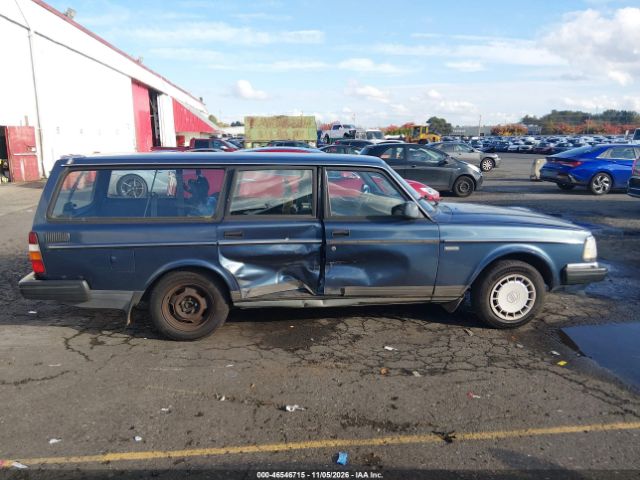
Insurance Offer: $1,741.00
Settlement: $6,067.60
Increase: $4,326.60 (+248.5%)
Key takeaway: Through the invocation of the appraisal clause, Leverage Auto Appraisals helped Ty E. increase the total loss settlement for a 1991 Volvo 240 from an initial offer of $1,741.00 to a final settlement of $6,067.60, representing a $4,326.60 (248.5%) net increase.
Does your own total loss offer look too low? Send us the report and tell us what concerns you.
The Claim
Following a loss on October 28, 2026, Ty E. sought a fair market valuation for their 1991 Volvo 240 in Portland, Oregon. State Farm declared the vehicle a total loss and presented a valuation report to determine the settlement amount. When the initial offer did not align with the owner's understanding of the current market for vintage European sedans, Ty E. engaged Leverage Auto Appraisals to perform an independent review and initiate the appraisal clause process.
About the Vehicle
The subject vehicle is a 1991 Volvo 240, a model noted for its longevity and a dedicated enthusiast following. This specific vehicle featured a 5-speed manual transmission, a drivetrain configuration that often distinguishes it from the more common automatic variants found in the used car market. Maintaining the integrity of such a classic requires an accurate assessment of its specific mechanical configuration and regional desirability.
The Insurance Valuation
State Farm provided an initial valuation of $1,741.00 based on a CCC ONE market valuation report. This report serves as the foundation for the carrier's settlement offer, utilizing automated data to compare the subject vehicle against others recently sold or listed for sale. In this instance, the report relied on a narrow set of data points to arrive at the four-figure valuation.
What Our Review Found
Upon reviewing the CCC ONE report, we identified several items that, in our opinion, warranted further scrutiny. The report utilized comparables located more than 500 miles away from Portland, which we alleged failed to accurately reflect the Pacific Northwest market.
We also noted that Comparable 2 featured an automatic transmission, differing from the subject's 5-speed manual drivetrain. In our view, drivetrain differences heavily impact market appeal and base value. Additionally, the report applied uniform condition deductions across multiple comparables. We believe it is statistically unlikely that independent vehicles would require identical dollar-for-dollar adjustments for condition. Finally, the comparables showed mileage differences exceeding 10,000 miles compared to the subject vehicle, requiring mathematical adjustments that we alleged introduced potential errors into the final calculation.
The Appraisal Process
Because the owner disagreed with the carrier's valuation, they invoked the appraisal clause—a contractual right within the insurance policy designed to resolve disputes over the amount of loss. This process involved the carrier's selected appraiser and Leverage Auto Appraisals performing independent assessments. The goal of this process is to move beyond automated software adjustments and focus on verified market data and the specific attributes of the loss vehicle.
Our Independent Market Analysis
Our analysis focused on the specific value drivers of a 1991 Volvo 240. We prioritized identifying vehicles with the manual transmission and sought to understand the local demand in Portland and the surrounding region. By focusing on the unique mechanical specifications and adjusting for the actual market conditions for classic Volvos, we provided a comprehensive valuation that accounted for the discrepancies found in the initial insurance report.
The Result
The appraisal process concluded with a significant adjustment to the vehicle's value. The original offer from State Farm was $1,741.00. The final settlement reached $6,067.60. This resulted in a net increase of $4,326.60, or 248.5%, for Ty E. This case demonstrates the importance of verifying that a total loss valuation accounts for specific drivetrain configurations and accurate geographic market data.
Local Market Perspective
In a market like Portland, OR, buyers of vintage European vehicles often look toward Seattle, WA, or Eugene, OR, to find comparable replacements. These cities share a similar climate and a high concentration of Volvo enthusiasts, which can drive prices significantly higher than in other regions of the country. A valuation that relies on data from hundreds of miles outside this corridor may fail to capture the local premium placed on well-maintained manual-transmission models.
Every total loss claim is different. Prior results do not guarantee a particular outcome.
LEVERAGE™ | KEN NIX
The Guy They Can’t Hire.
The Total Loss Expert You Can.
One man. Five skill sets. Zero insurance company loyalties.
I’m Ken Nix. I work for vehicle owners, not insurance companies. I look at the vehicle, the evidence behind the report, and the reasoning behind the offer.
Investigator. Hacker. Strategist. Negotiator. Appraiser.
All consumer advocate.
My programming background helps me question calculations and spot patterns. My automotive experience helps me determine whether the vehicles in a report actually compare to yours.
Experience on your side.
200-plus five-star reviews
Read our customers’ experiences →
16-plus years negotiating vehicle claims
40-plus years of automotive sales, vehicle appraisal, and negotiation experience
Understand your options.
Start with the information that matters to your claim.
Get the Advantage. Get LEVERAGE™.
Start with a free Red Flag Review. Send your insurer’s valuation report and tell us what concerns you. Let’s take a closer look at the vehicle details, comparables, and adjustments before you decide on your next step.
They have their experts. Now you have LEVERAGE™.

